Business Valuation & Advisory Report
Lakeshore Mechanical (fictional demo)
Valuation as of 2025-12-31 · Report date 2026-11-19 · Figures excerpted from the 54-page PDF
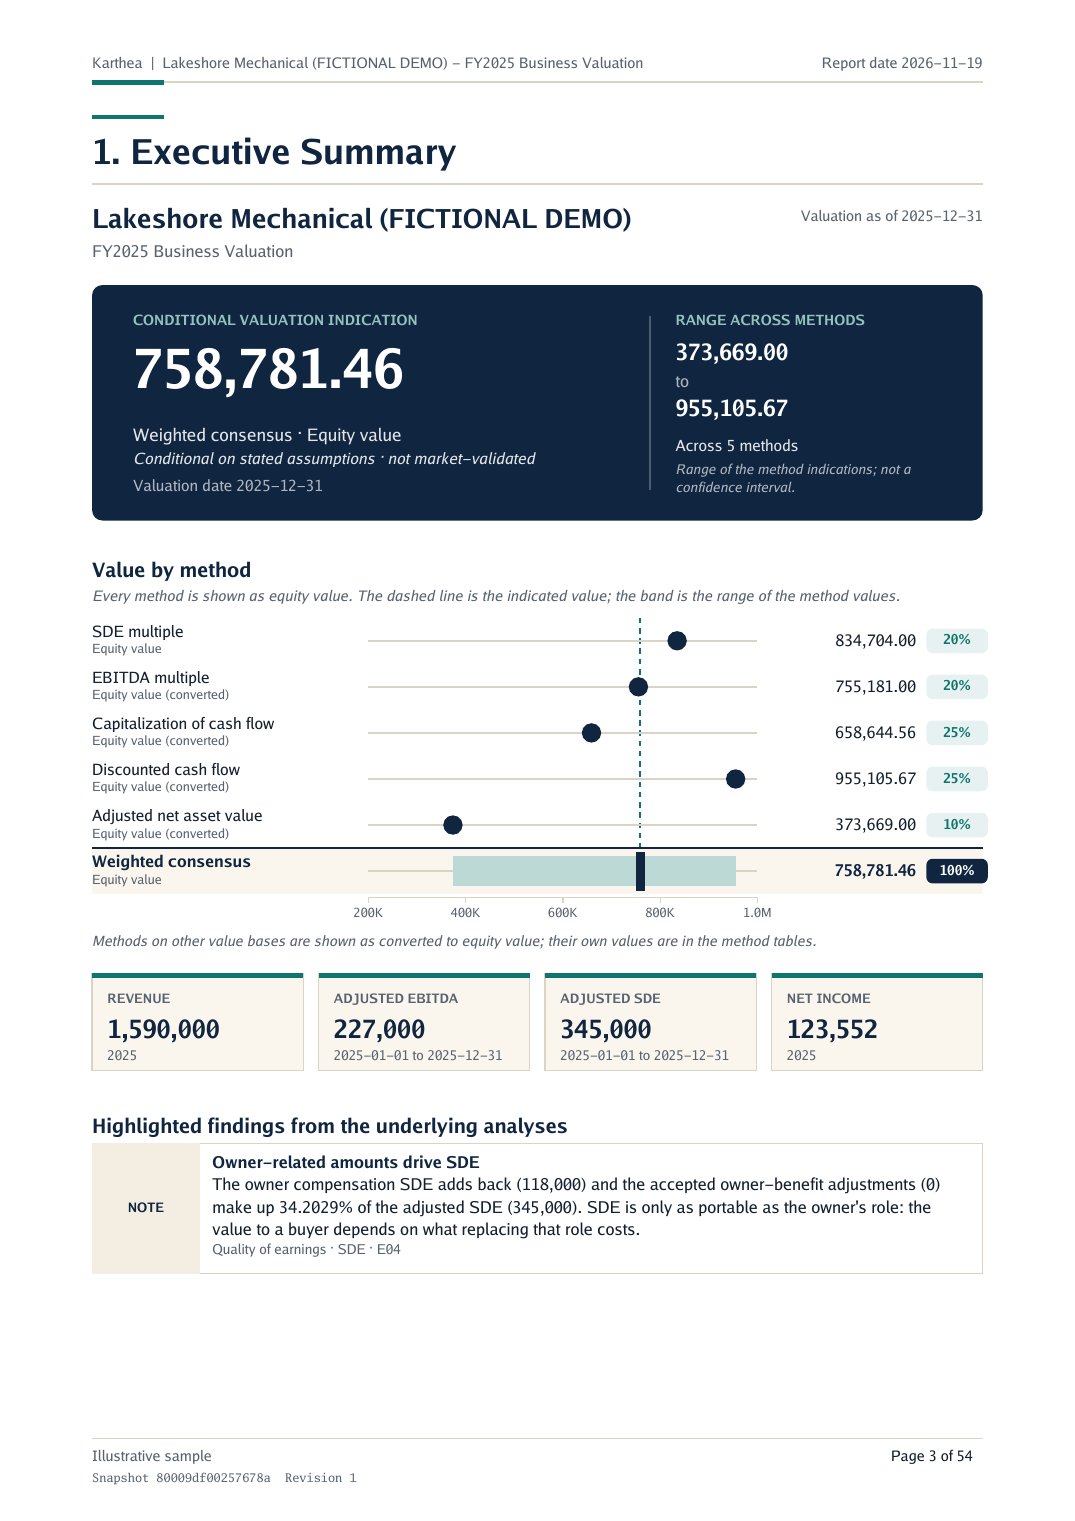
Conditional weighted equity-value indication (report page 3)
758,781.46
Weighted consensus of five methods, shown as equity value. An illustrative, assumption-based equity-value indication, supported by five valuation methods and detailed financial analysis.
The range across the five equity-basis method indications is 373,669.00 to 955,105.67. It is the spread between the lowest and highest method, not a confidence interval, a fair market value range or a probability band.
Financial Overview
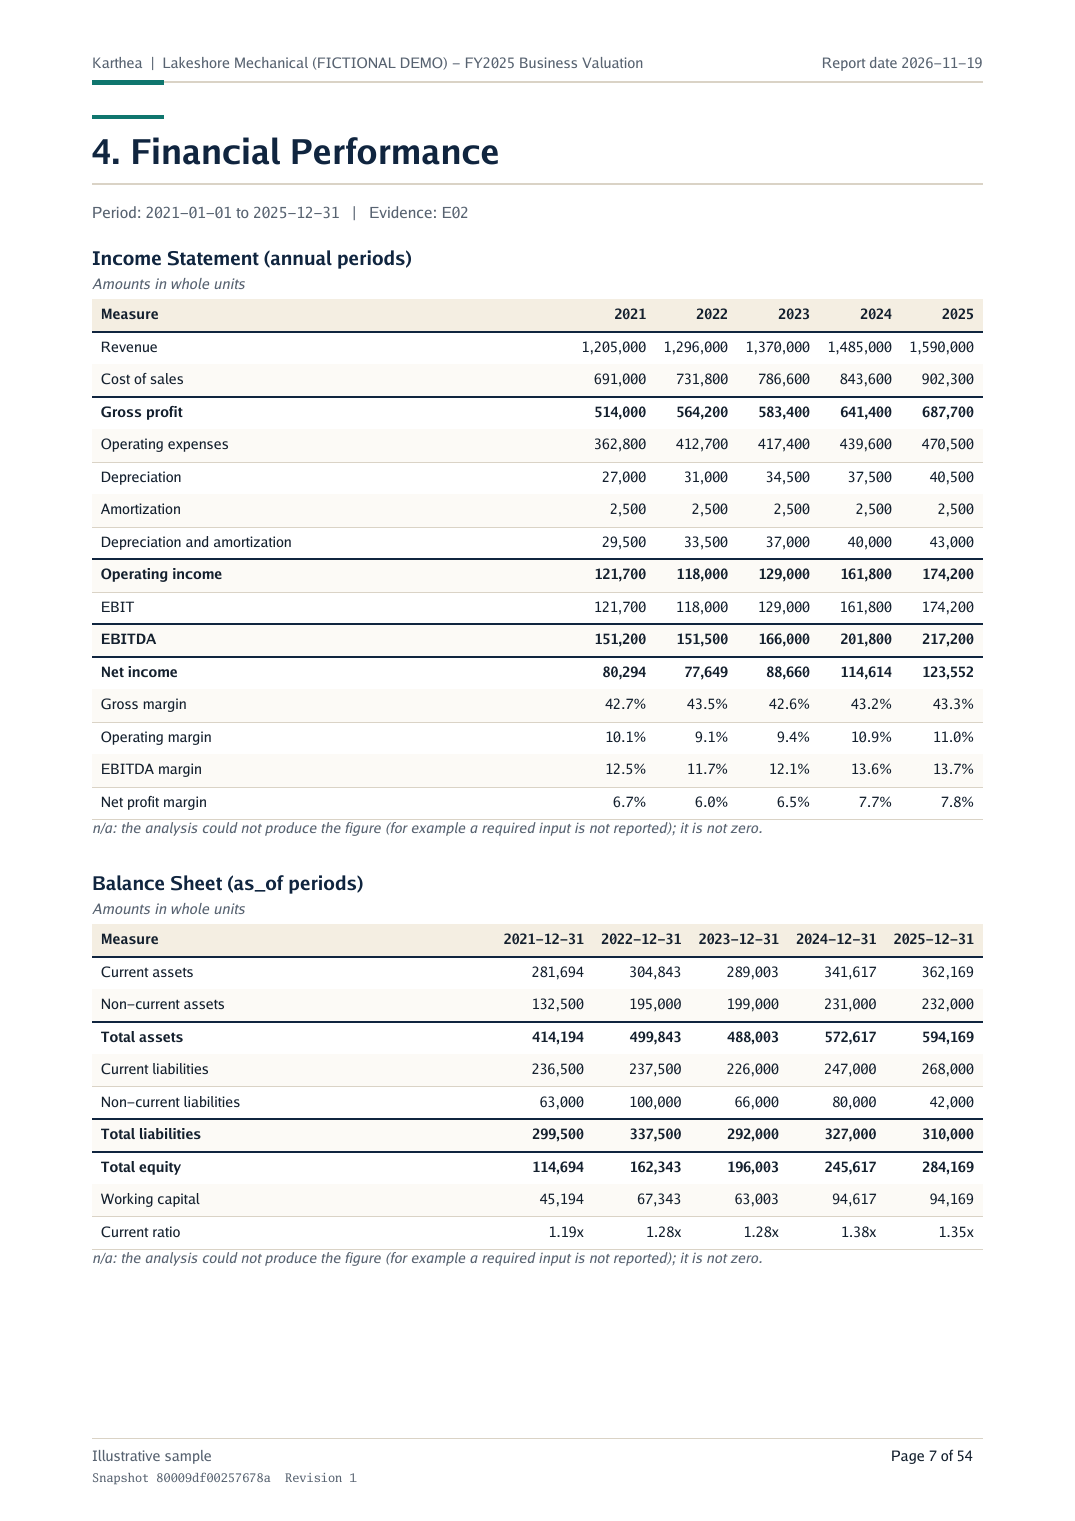
Five historical years, 2021 to 2025, from the statements in the report.
| Measure | 2021 | 2022 | 2023 | 2024 | 2025 |
|---|---|---|---|---|---|
| Revenue | 1,205,000 | 1,296,000 | 1,370,000 | 1,485,000 | 1,590,000 |
| Gross profit | 514,000 | 564,200 | 583,400 | 641,400 | 687,700 |
| Operating income | 121,700 | 118,000 | 129,000 | 161,800 | 174,200 |
| EBITDA | 151,200 | 151,500 | 166,000 | 201,800 | 217,200 |
| Net income | 80,294 | 77,649 | 88,660 | 114,614 | 123,552 |
Methods
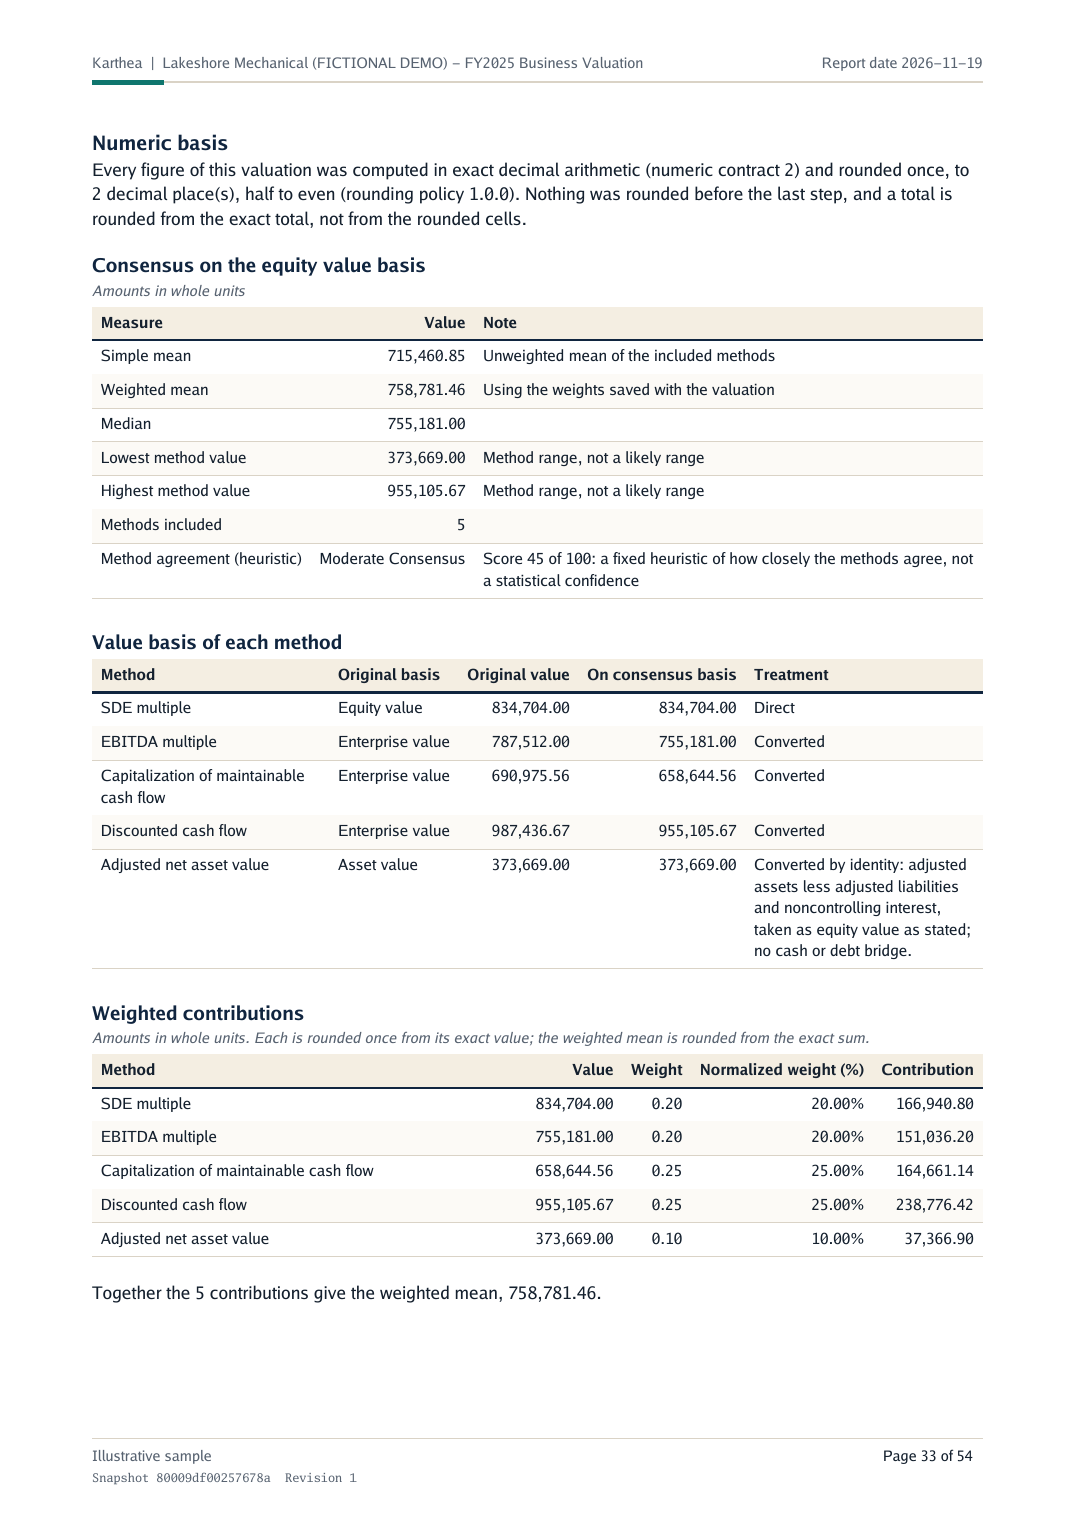
Five methods, each shown on the equity-value basis. Methods that start from enterprise or asset value are converted to equity value in the report.
| Method | Weight | Treatment | Equity-basis value |
|---|---|---|---|
| SDE multiple | 20% | Direct (equity value) | 834,704.00 |
| EBITDA multiple | 20% | Converted from enterprise value | 755,181.00 |
| Capitalization of cash flow | 25% | Converted from enterprise value | 658,644.56 |
| Discounted cash flow | 25% | Converted from enterprise value | 955,105.67 |
| Adjusted net asset value | 10% | Converted by identity from asset value | 373,669.00 |
| Weighted consensus | 100% | Equity value | 758,781.46 |
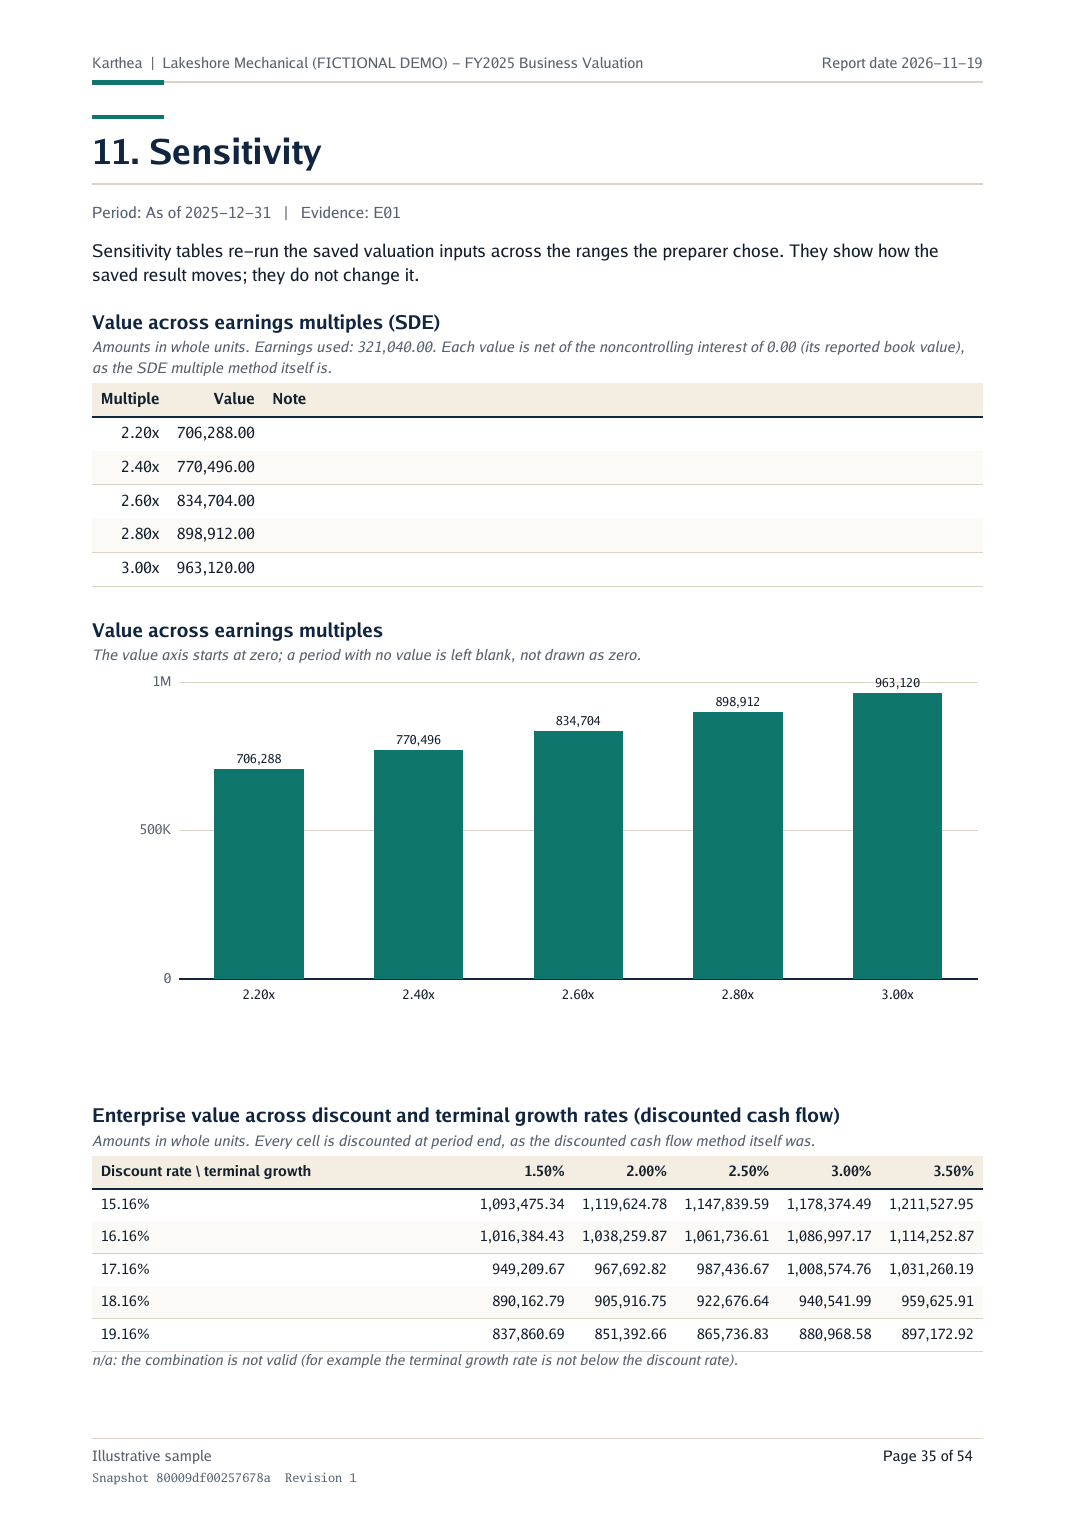
Sensitivity (report page 35): on earnings of 321,040.00, the SDE multiple method gives 706,288.00 at 2.20x and 963,120.00 at 3.00x.
Highlighted findings
The analyses behind the report raised 2 findings: 0 critical, 0 warning and 2 informational.
- Owner-related amounts drive SDE. The owner compensation that SDE adds back (118,000) and the accepted owner-benefit adjustments (0) make up 34.2029% of the adjusted SDE (345,000). The value to a buyer depends on what replacing the owner's role costs.
- Discounted cash flow rate basis. The discount rate is customer-confirmed as a whole-enterprise rate and is not independently verified. Confirming the basis does not make the rate defensible or a market rate.
Assumptions and evidence
- The multiples, rates and assumptions in this illustrative sample are person-supplied and are not independently validated against the market.
- The indication is conditional on the stated assumptions, which the report lists.
- The report lists its scope and limitations on page 5.